

Heavy farmer selling, higher carrying costs and rising freight rates are increasing liquidity risks for grain merchandisers in 2026/27.
Knowledge Exchange
Coverage spanning grain and farm supply, including oilseeds and renewable fuel dynamics.
Heavy farmer selling, higher carrying costs and rising freight rates are increasing liquidity risks for grain merchandisers in 2026/27.
U.S. biofuel demand is rising as mandates and 45Z tax credits boost soybean oil use and ethanol production, increasing import and export needs.
Soaring diesel and fertilizer costs are outpacing crop-price gains, squeezing farm margins and forcing difficult, high-stakes decisions for the 2027 crop year.
Tight grain supplies, strong demand and geopolitical risks are driving volatility across global corn, soybean and wheat markets.
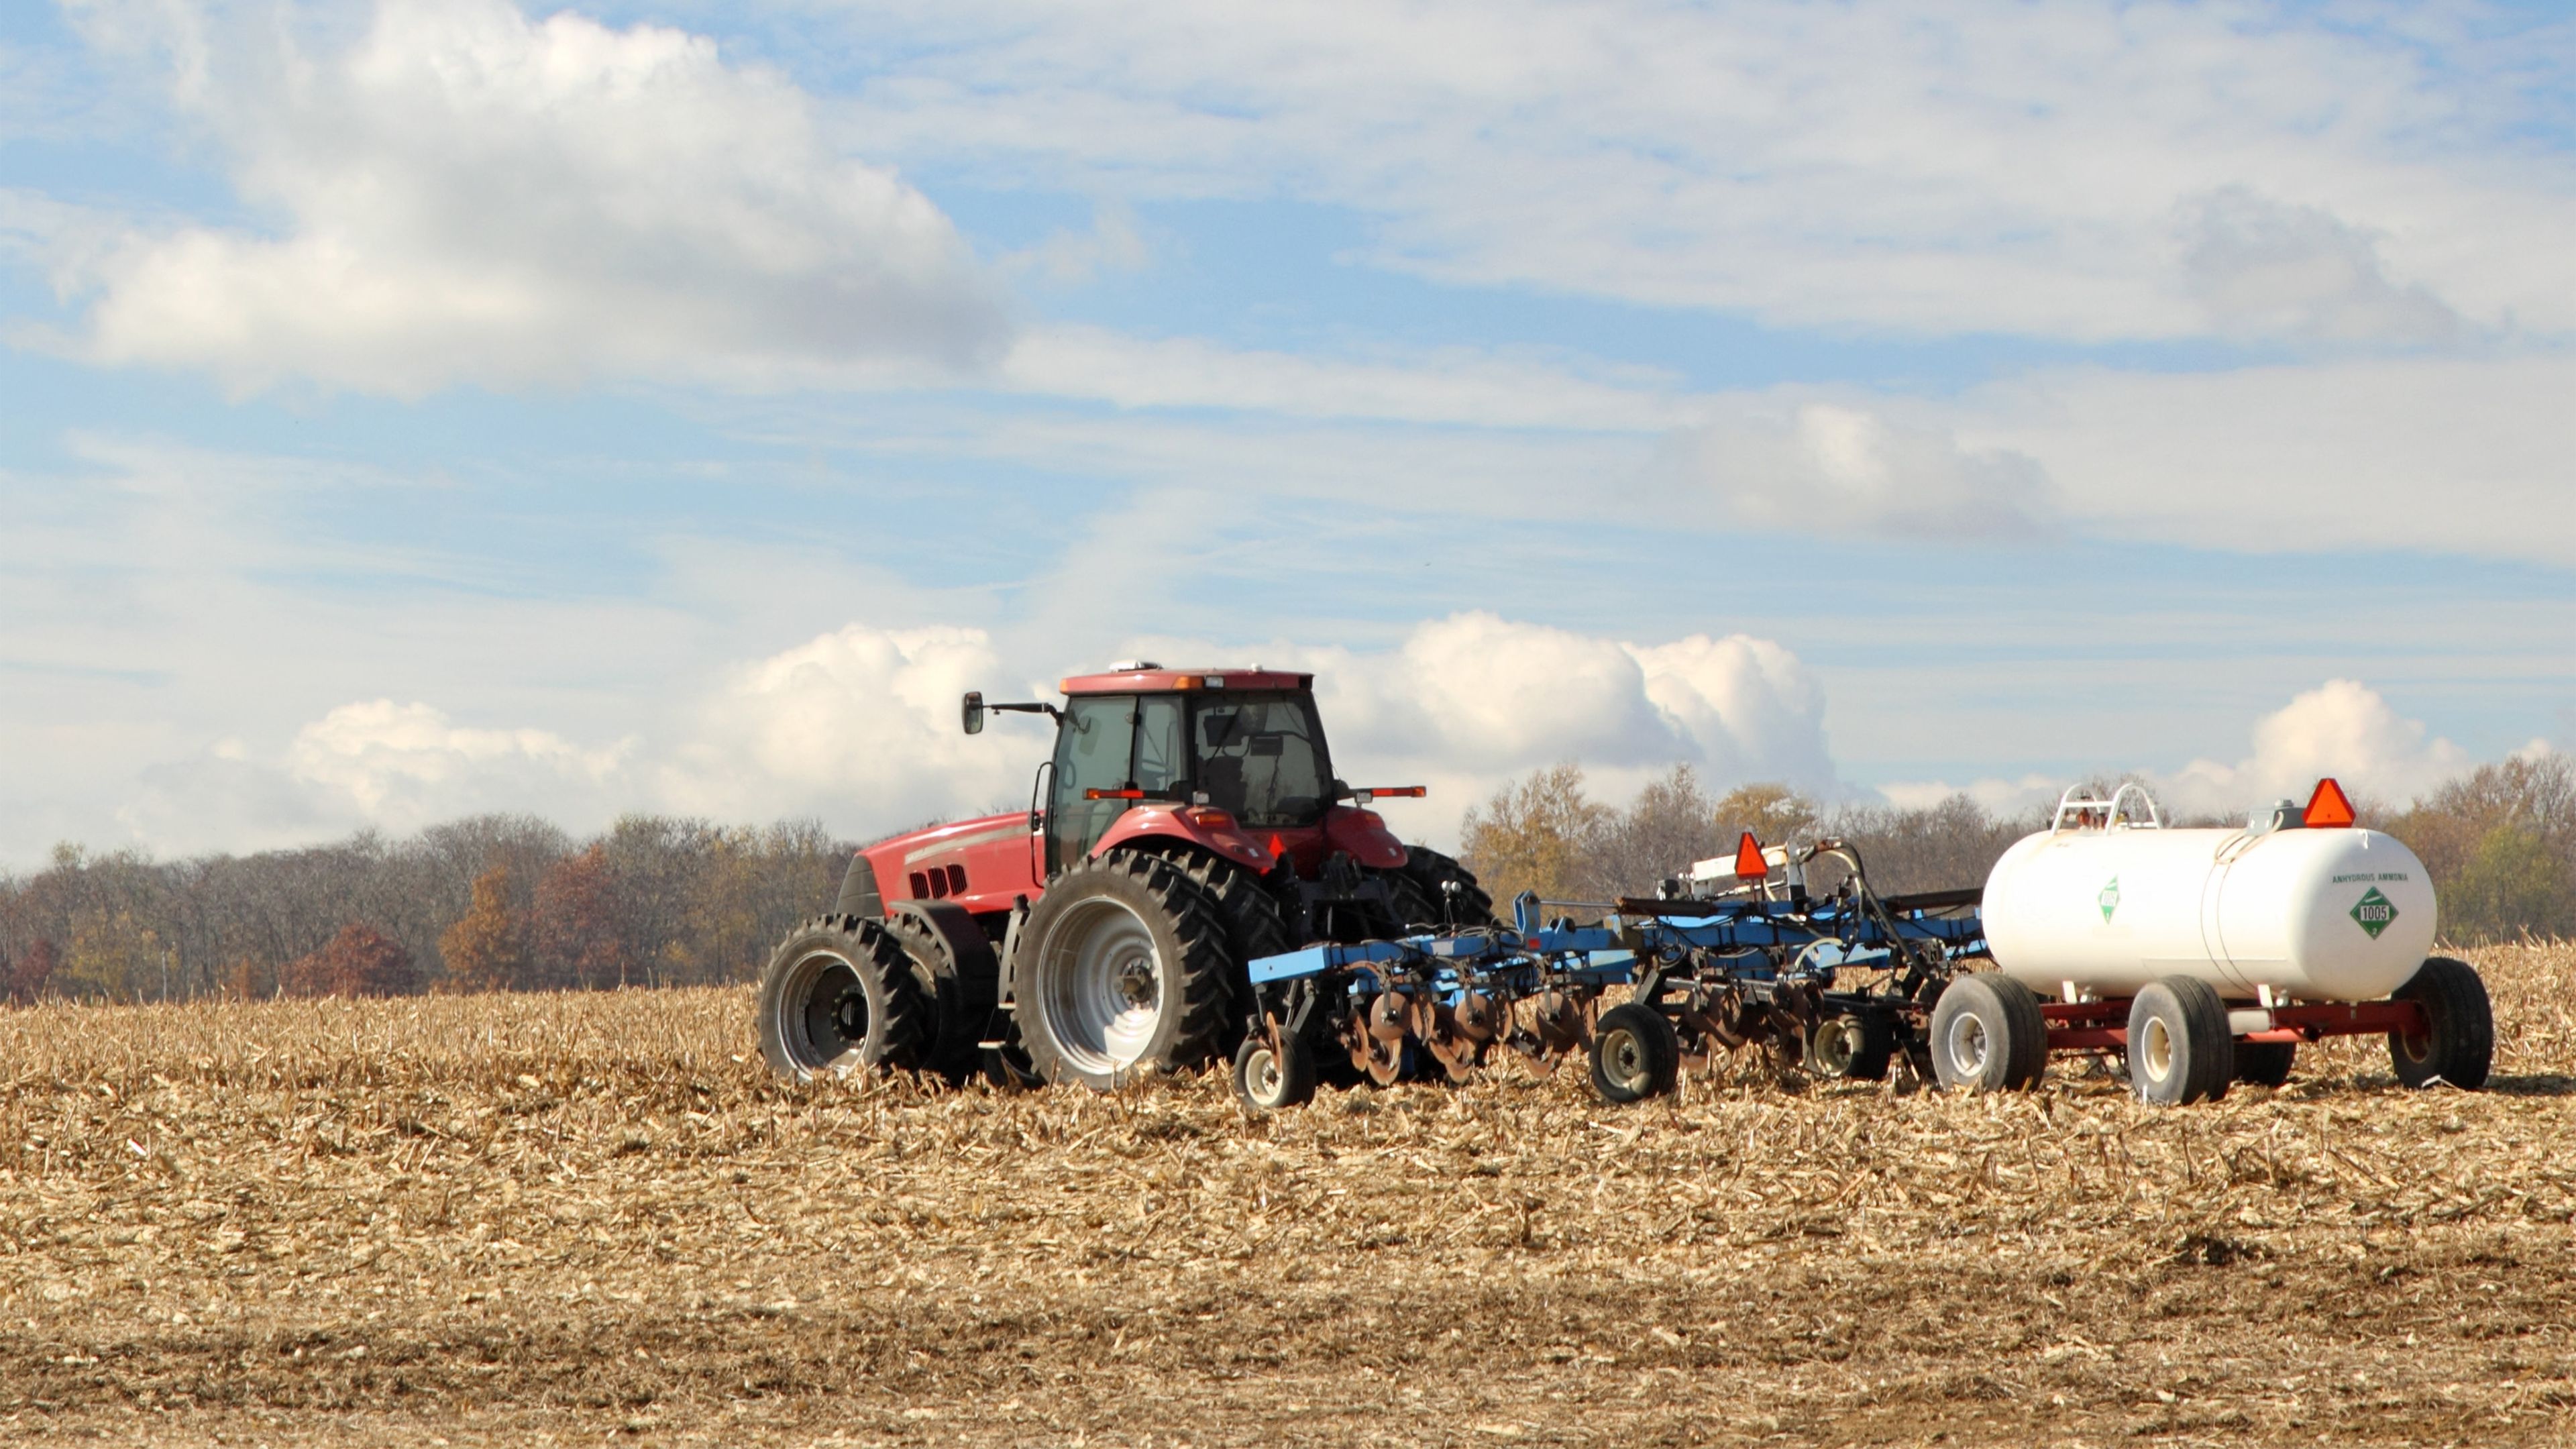
Unlike the 2022 fertilizer shock, today’s disruption is longer term. Geopolitics and supply chain issues are spiking prices and complicating sourcing.
Refiners face mounting pressure to meet ambitious biofuel blending mandates as RIN markets, feedstocks and policy uncertainty shape compliance.
U.S. grain markets face pressure from weak corn prices, record soybean crush, weather risks and winter wheat quality concerns.
Tight farmer margins and elevated input costs could slow crop input buying and challenge agricultural retailers’ inventory planning.
The wait is over for the renewable volume obligations of the Renewable Fuel Standard, clearing an outlook that had been clouded by uncertainty the last several months. On March 27, the White House announced RVOs for 2026 and 2027 at the highest levels in the program’s 20-year history, intended to increase the use of domestic biofuels.
Cotton farmers plan to expand acreage as prices forge a mild recovery. Long-grain rice acreage is projected to be smallest since 1983 as farmers shift acres to soybeans. Global abundance of sugar is bearing down on prices, discouraging U.S. farmers from expanding sugarbeet acreage.
Market volatility offered farmers new marketing opportunities in grains and oilseeds in the first quarter. Farmers plan to shift acres to soybeans in 2026 and away from corn and wheat. Drought is again plaguing the U.S. winter wheat crop, and producers look to El Nino for potential relief.
The longer the political uncertainty endures in the Middle East, the greater the lasting impact of stalled fertilizer and oil production. Fuel and fertilizer prices have increased 20%-40% since the conflict began, and buyers who delayed decision making are more exposed. Improved commodity prices are not anticipated to offset higher farm supply prices. Ongoing supply chain disruptions for urea could recreate 2022-level fertilizer prices without 2022 crop-price support.
Get relevant and actionable insights from CoBank's industry-leading Knowledge Exchange research team.
Get relevant and actionable insights from CoBank's industry-leading Knowledge Exchange research team.